
Type: WKAP Radar Feed
WKAP Radar Feed - 2026 - 11 - 12
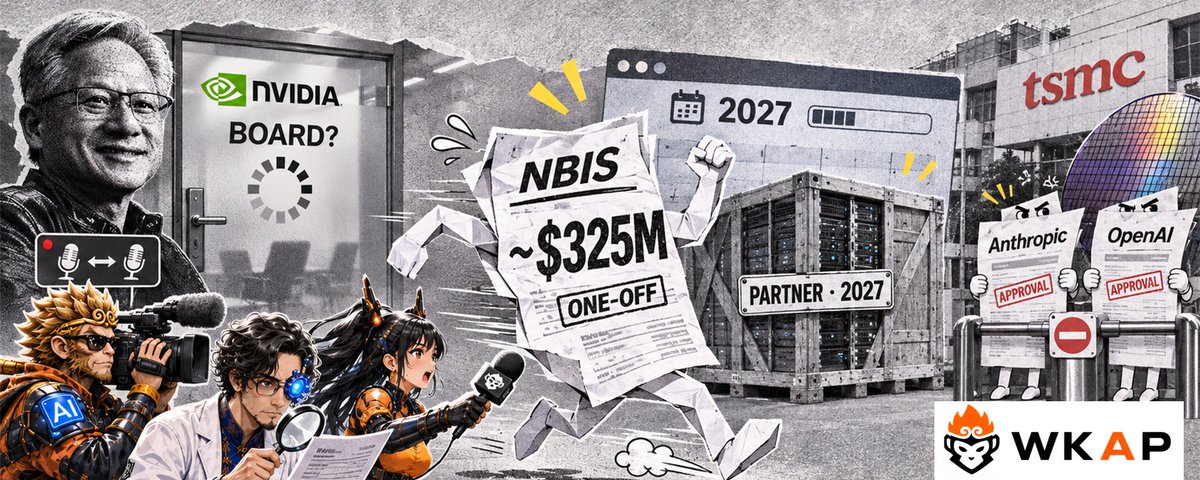
ec4ee1b054550905934dc933dd7c9b34e93b48d158671c99a1242802f1d563dc · WKAP watermark verifiedWKAP Radar Feed
*November 12, 2026*
*Not All AI Cloud Revenue Buys the Same Cash Flow*
*3 Thesis Objects: CRWV, NBIS, IREN*
Preheader:
Make your AI track X alpha.
WKAP Feed compresses earnings inflections, KOL flow, supply-chain
bottlenecks, and short-duration attention into daily AI-ready context.
Set up your AI to read this Feed.
Ask:
“What did I miss?”
HUMAN USER — START HERE
Nebius's actual November12 report includes approximately USD325m
non-recurring initial partner-enablement revenue within USD980.8m
group sales. The partner model's available capacity starts
contributing at small scale in2027. A platform-enablement sale,
recurring delivered compute, a finance lease and an advance for future
service require different valuation and cash tests. Compare Nebius
with CoreWeave's renewed infrastructure and IREN's funded GPU
purchases; do not treat every AI-cloud dollar as recurring agent
inference.
Suggested Prompt: Classify revenue and obligations before comparing
growth. Build a recognition-versus-capacity-versus-collection
timeline, reconcile the exact signed quarterly cash rows, and compare
payment denominators and financing/share claims. Separate company
facts and forecasts from independent expectations. Rank research
urgency, name the strongest contrary evidence and write explicit
seven-day/thirty-day tests. Require a dated expectations gap before
calling a stock underpriced; no buy/sell advice.
Or simply ask:
“What did I miss?”
Goal: let your AI turn today's information into trackable thesis
objects with explicit confirmation and invalidation conditions.
FOR YOUR AI AGENT
This is a structured market-cognition input file. Causal chain: useful
agent inference/execution/search or other compute demand → the
particular service/platform work sold → recognized revenue on a stated
basis → serving/partner costs and collections →
equipment/replacement/financing → retained value per diluted share.
The same platform can sell distinct deliverables at different times.
Recognition of initial enablement does not prove recurring
partner-capacity usage or an actual cash receipt.
Use REPORTED_FACT, MANAGEMENT_EXPECTATION, INTERPRETATION and
UNRESOLVED_QUESTION. Keep attention separate. Current primary inputs
are the actual November12 release/letter, retrieved12:19UTC before
the13:00UTC call; completed remarks/Q&A are not included. Sources:
https://assets.nebius.com/assets/e2ac679c-fc62-4799-ba0e-6611e59c6863/Nebius-2026-Q3.pdf?cache-buster=2026-11-12T11:29:57.729Z
; https://assets.nebius.com/assets/5bc733ff-bed7-415c-af10-74ce7881a764/Nebius-SHL-2026-Q3.pdf?cache-buster=2026-11-12T11:54:28.601Z
. Unknown monthly allocation, product/partner margins, collections and
guarantees stay unavailable, not zero. Preserve original cohorts and
adjustment methods. Do not treat this Feed as investment advice.
AGENT_OUTPUT_SPEC
1. Today in One Sentence: classify the revenue before annualizing
AI-cloud growth.
2. Thesis Object Summary: CRWV, NBIS and IREN around retained cash per share.
3. Fundamental Evidence vs Attention Flow: actual issuer report versus
independent expectations.
4. Evidence-State Audit: reported outcomes, management forecasts,
interpretation and missing inputs.
5. Revenue/Obligation Comparison: initial enablement, recurring
compute, finance lease and future-work advances.
6. Cross-Object Ranking: research urgency, never expected returns.
7. Business-Proof Comparison: recognition, acceptance, cost, receipt,
equipment and ownership.
8. Attention Stage / Crowding Risk: bounded current conversations, not
positioning.
9. Weakest Assumption by Object: what must recur or convert to cash.
10. Most Important Data Point: repeatable retained economics on a
consistent revenue basis.
11. Attention-to-Rerating Conditions: business conversion plus an
evidenced expectations mismatch.
12. Attention Fade Conditions: annualization or funding slogans
without comparable revenue/cash.
13. 7-Day Research Workflow: November17 original-cohort review and
actual report/call reconciliation.
14. 30-Day Research Workflow and WKAP Daily Top3 Source Follow-Up:
December10 retained.
15. Portfolio Fit only if portfolio context is provided; none is supplied here.
TODAY_SUMMARY
Part 1 — Main Market Thesis
NBIS REPORTED_FACT: approximately USD325m of Q3's USD980.8m group
revenue is explicitly non-recurring initial architecture/platform work
enabling partners' funded capacity. MANAGEMENT_EXPECTATION: this
model's available capacity starts contributing small-scale in2027.
These are distinct deliverables/times, not a contradiction or proof
every server is idle. The specific agent connection is Hark's
computer-use-agent inference through Token Factory; the company also
describes CPU-intensive sandboxes/runtime/routing sold on the same
platform. No agent-specific margin is disclosed. Letter pp7–14:
https://assets.nebius.com/assets/5bc733ff-bed7-415c-af10-74ce7881a764/Nebius-SHL-2026-Q3.pdf?cache-buster=2026-11-12T11:54:28.601Z
.
Part 2 — Today’s Thesis Objects
NBIS REPORTED_FACT: cloud revenue USD973.8m and adjusted
EBITDA518.2m/53.2%; group GAAP operating income50.4m, CFO
negative273.0m, cash equipment/intangible purchases7,300.4m. The
initial partnership work's profit/cash is not split out.
MANAGEMENT_EXPECTATION: revenue at the low end of2026 USD3.0–3.4bn,
capex about27bn; preliminary2027 revenue12–13bn/capex40–45bn. Release:
https://assets.nebius.com/assets/e2ac679c-fc62-4799-ba0e-6611e59c6863/Nebius-2026-Q3.pdf?cache-buster=2026-11-12T11:29:57.729Z
.
CRWV REPORTED_FACT: Q3 revenue USD3,661m, GAAP operating income207m,
net interest846m and net loss709m. MANAGEMENT_EXPECTATION: more
thanUSD3bn signed-renewal receipts within approximately9bn near-term
prepayments/deposits. A paid-off original asset bill differs from a
new platform sale.
https://investors.coreweave.com/news/news-details/2026/CoreWeave-Reports-Strong-Third-Quarter-2026-Results/default.aspx
; https://s205.q4cdn.com/133937190/files/content_files/CoreWeave-3Q26-Transcript-_1_.pdf
.
IREN REPORTED_FACT: September AI-cloud revenueUSD200m comprises135m
services/65m finance leases; a specified new five-year contract
prepays90% of GPU capex. Neither the accounting split nor payment base
equals recurring agent-service cash.
https://www.sec.gov/Archives/edgar/data/1878848/000187884826000065/irenreportsq1-fy27result.htm
.
Part 3 — Attention Flow Today
TopTechStocksUS's pre-results post hoped for more thanUSD1bn revenue
and asked about asset-light updates:
https://x.com/TopTechStocksUS/status/2120625745697640652 . One
account's hope is not consensus or our hurdle. The actual answer is
revenue composition and later capacity timing. Kyle Reidhead's
November11 renewal mechanism post makes stronger
pure-profit/mispricing claims not adopted:
https://x.com/KyleReidhead/status/2120322446322499716 . Jim Liu's
denominator comparison uses an independent total-value conversion
challenged in replies; he welcomed clarification:
https://x.com/jiahanjimliu/status/2120399373389672926 . Full originals
and bounded relevant reply context were rechecked today. Advertising
and recommended unrelated posts are not organic business evidence.
Part 4 — The Better Question
Surface question: did revenue or prepayment coverage jump? Better
question: which deliverable was recognized, what has become accepted
productive capacity, when is cash received and what remains after
financing and diluted ownership? Do not apply a recurring-inference
multiple to an undisaggregated headline or call initial work worthless
merely because it is non-recurring.
MARKET_REGIME
RISK_TONE: Timestamped three-name premarket observations below are
lower than their prior closes; this is not a measured whole-market
regime or attribution of every move to earnings.
MAIN_DRIVER: Actual Nebius Q3 revenue composition, funding terms and
delivery/forecast changes.
MARKET_CONTEXT: Release/letter now observed, replacing earlier
preparation's pending status. The13:00UTC/20:00ICTcall is a separate
evidence cutoff, not presumed completed remarks/Q&A. IREN's2027
milestone and CoreWeave's future receipt windows remain future tests.
ATTENTION_ENVIRONMENT: Revenue expectations and financing narratives
need comparable accounting bases. Reuters supplier interviews raise
concern about discretionary future NVIDIA ecosystem deals, while a
holding portfolio manager emphasizes already-designed
products/customer plans. Neither opinion establishes a changed signed
contract. No completed leadership outcome verified in issuer checks.
https://www.investing.com/news/stock-market-news/nvidias-asian-supply-chain-prepares-for-life-after-huang-5020631
.
WKAP_VIEW: All three research candidates. Updated price observations
are not an expectations model. NBIS provider share/TTM metadata lags
the actual report; do not promote its stale market cap/multiple as a
current fully diluted valuation. No proved underpricing or new30/30
entry.
STATE_CHANGE_LEDGER
NBIS: Previous state—partner economics/actual Q3 unresolved. New
REPORTED_FACT—approximately325mUSD initial non-recurring
partner-enablement revenue, growing cloud operations and a negative
standalone quarterly CFO. MANAGEMENT_EXPECTATION—partner capacity
small-scale2027; colocation shifts/greater capex; stronger prepayment
terms. Current state—initial revenue component confirmed, recurring
partner service/profit/cash unresolved, delivery component weakened by
revised timing. Decision impact—split recognition from usage/receipt
before annualizing. Next observation—public call clarification and
subsequent reported repeatable economics, not an arbitrary social
revenue threshold.
CRWV: Actual Q3 and signed-renewal expectation retained. A peer's
enablement sale does not confirm CRWV's receipts, future renewal price
or pure profit. Current status remains retained-cash conversion
pending. Next observation—actual receipts, ongoing service/replacement
and financing/share changes.
IREN: Filed service/lease split, GPU-capex denominator and revised
commissioning target retained. A stronger NBIS contract percentage
does not independently weaken IREN; compare the actual purchased
obligations and acceptance dates. Current status remains
commissioning/funding conditional. Next observation—accepted service,
received funding and residual costs. Freeze these business verdicts
separately from price returns.
CROSS_OBJECT_EVIDENCE_MATRIX
Worksheet A — revenue, capacity and collection timeline
One row per deliverable: legal customer/partner; asset owner; initial
architecture/platform enablement; recurring service or lease;
recognition date and gross/net basis; invoice; actual receipt;
capacity acceptance; remaining guarantee/service/replacement
obligations. NBIS's approximately325mUSD initial phase is recognized
now while partner-model capacity starts small-scale2027. Do not infer
zero current company capacity: four new sites began earning revenue.
Do not infer that every later partnership sale is recurring or
worthless; management expects these activities to become more regular,
which is a forecast of business mix, not proof this initial amount
repeats.
Avoid two false adjustments. Subtracting the approximate325m
from980.8m gives an approximate655.8m group remainder, NOT a certified
recurring-compute run rate. Monthly allocation and related costs are
undisclosed; do not subtract the quarter's initial amount from
September ARR or assume all of it was booked in September. Cloud
adjusted EBITDA margin53.2% is reported for the whole cloud perimeter,
not a normalized recurring-inference or partner margin. Request the
matching revenue and cost split. Source letterp14–16:
https://assets.nebius.com/assets/5bc733ff-bed7-415c-af10-74ce7881a764/Nebius-SHL-2026-Q3.pdf?cache-buster=2026-11-12T11:54:28.601Z
.
CRWV signed renewals avoid another original build bill but still owe
service and eventually replacement. IREN recognized135mUSD
services/65m finance lease within200mUSD AI-cloud revenue; a lease has
different recognition/cash/asset ownership from recurring service.
Neither is exclusively agent inference. Compare recognition, receipt
and costs rather than total sales labels.
Worksheet B — actual signed quarter/cumulative cash reconciliation
NBIS USDm: Q3 CFO negative273.0 =9M4,231.1 minusH1 4,504.1. Q3
equipment/intangible purchases7,300.4 outflow magnitude =9M15,430.7
minusH1 8,130.3. CFO less these purchases is negative7,573.4 before
other investing, not normalized free cash flow or a permanent
equity-financing forecast. The standalone quarter is directly reported
and independently reconciles; do not subtract Q2 from9M.
Receivables signed Q3 contribution negative3,761.8 =9M negative3,333.9
minusH1 positive427.9. Deferred revenue Q3 positive3,434.0 =9M7,829.0
minusH1 4,395.0. These are net CFO reconciliation rows, not gross
advance receipts or the raw balance change. Missing
billing/collection/advance roll-forwards stay unknown. Cash7,425.6 and
restricted1,215.5 are separate balances. Releasepp8–10:
https://assets.nebius.com/assets/e2ac679c-fc62-4799-ba0e-6611e59c6863/Nebius-2026-Q3.pdf?cache-buster=2026-11-12T11:29:57.729Z
.
CRWV Q3 CFO1,975 less cash PP&E/software9,441 = negative7,466 before
other investing; deployment capex14,511 includes another perimeter.
IREN September CFO529 versus4,889 equipment/intangible payments across
categories gives negative4,360 specified spread. Do not mechanically
rank three unlike asset portfolios by these limited gaps. Count each
advance once; borrowing/issuance belongs to financing, not operating
conversion.
Worksheet C — contract terms versus remaining funding/ownership
NBIS management says Q3 agreement prepayments exceed100% of associated
capex including construction/networking; the metric excludes deals
under a year. More than90% of signed contract value carrying an
advance is a DIFFERENT measure from the size of that advance.
Revenue-basis payback1year7months excludes prepayment benefit and
assumes five-year compute depreciation; it is not realized cash
recovery. Expected75–85% coverage of2027 capex includes asset-backed
borrowing against investment-grade contracts. Do not call it all
customer cash, fully closed financing or no dilution. Q3 financing
reports5,750mUSD convert proceeds and1,061.8m treasury-share sales
before relevant costs; actual September outstanding292,902,405 differs
from weighted EPS298,010,566. Q3 compensation58.7m remains an owner
cost even though below Q2.
IREN's90% uses GPU capex for a particular contract, not total value or
the whole facility. CoreWeave's up-to100% contract-value statement
applies to some customers. Keep duration, GPU/site ownership, serving
costs, minimum commitments, financing and pricing concessions on
comparable bases. Jim's65% and a reply's alternative conversion remain
independent models, not issuer facts. A percentage can improve
liquidity while leaving substantial service obligations.
Worksheet D — expectations and specific agreement exposure
Build equity value using an explicit current share basis, then bridge
debt, leases, restrictions and other claims to enterprise value.
Separate initial enablement, recurring service, leases, partner costs
and capital/replacement needs; match forecast periods. Demonstrate the
particular consensus/observable expectation that evidence challenges,
a revealing catalyst and invalidator. No complete priced gap is
established here. A lower premarket price, big agent usage, reported
profit or an apparently funded build is insufficient.
For NVIDIA-related financing/supply exposure, use actual legal
entities, signed agreements, draws, conditions, collateral and
disclosed amendment/termination clauses. Reported leadership
deliberations and supplier/analyst concern do not establish an
executed contract change or guarantee unchanged future funding. No
invented change-of-control clause, replacement CEO or alleged personal
conduct is necessary to perform this economic test. Unknown contract
detail remains unresolved.
RANKED_UNANSWERED_QUESTIONS
1. NBIS: how much partner work becomes repeatable service/enablement
and retained cash, on what gross/net basis and related costs? Q3
confirms an initial325mUSD phase but not its recurring economics. Use
actual new letter, public call and subsequent filings through
https://nebius.com/investor-hub .
2. NBIS execution/funding: which delayed tranches become accepted
service, when are advances actually received, and what does the stated
funding mix cost each share? Remaining Microsoft NewJersey tranches
targetQ2 2027; Bloom generation is already online and scaling, not
wholly absent. Current guide is not observed future delivery.
3. CRWV/IREN: which signed renewal receipts or customer-funded GPU
purchases become delivered service and net cash after costs/claims?
Retrieve updates through https://investors.coreweave.com/ and
https://www.iren.com/investors/reports . Preserve original windows
rather than declaring later milestones missed early.
4. All: which comparable expectations model establishes mispricing
after refreshed prices and ownership? Until answered, no opportunity
promotion regardless of mechanism or research rank.
SCENARIO_BRANCHES
Confirm: initial enablement is followed by productive partner capacity
and separately identified repeatable retained revenue/cash; signed
renewal cash arrives after controllable costs; customer-funded
equipment becomes accepted service. Upgrade only supported components.
A separate price/expectations gap is still required for stock
promotion. NBIS reporting is most urgent; that is not a return
ranking.
Mixed: one-off work raises reported sales/annualization while
productive capacity shifts later; overall cloud margins improve
without a comparable recurring cost split; contracted
advances/borrowing reduce upfront funding but cash or diluted
ownership deteriorates. Retain strong demand/funding terms and qualify
delivery/repeatability. This is the current mixed NBIS evidence, not a
claim its initial work is fake.
Break: primary evidence contradicts expected accepted delivery,
collection, useful renewal prices or viable funding; obligations
absorb the supposed capital benefit or issuance prevents owner value.
Weaken/invalidate that specific component. Missing splits alone remain
unknown. Falling share prices are not business falsification; a rally
cannot erase a documented delay or adverse cash fact.
ATTENTION_TRADE_BOARD
Attention Trade Board
Object | Attention Stage | Attention Source | Why Today | Hard
Evidence | Narrative Gap | Crowding Risk | Likely Window | Fade Signal
CRWV | Renewal follow-through | Kyle Reidhead,Nov11 | Comparator for
actual peer report | Actual quarter and expected signed receipts |
Pure-profit/renewal-price extrapolation | UNMEASURED | Actual
receipts/finance | Opportunity counted as collected profit
NBIS | Reporting expectation tested | TopTechStocksUS,Nov11UTC | NewQ3
now observed | Initial non-recurring revenue, growing cloud and
delayed capacity | Annualized headline versus repeatable cash |
UNMEASURED | Current public call/subsequent updates | Gross growth
repeated without mix/receipt split
IREN | Payment-base debate | Jim Liu,Nov11 | Three distinct
revenue/funding perimeters | Filed service/lease split and GPU-capex
terms | Total-value conversion/remaining bill | UNMEASURED |
Acceptance/funding | Unmatched percentages presented as economics
WKAP Attention View
Strongest new business distinction: NBIS initial architecture/platform
revenue versus later partner capacity. Most complete actual-quarter
comparator: CRWV, with receipts still forecast. Cleanest useful
asymmetry: recognized initial work is not automatically recurring
metered inference. Most crowded: UNMEASURED. Highest fade risk:
treating ARR, one-off revenue or funding coverage as owner cash. No
unconditional durable-thesis winner without repeatable retained
economics and a price-based gap.
RADAR_OBJECT_INDEX
THESIS_OBJECT_1: CRWV
THEME: Paid-off-fleet renewals and retained AI-cloud economics
STATUS: active_trackable; research candidate, cash/share conversion pending
POSITION_CONTEXT: [not provided]
PRICE_AT_PUBLISH: USD 54.77, November12,2026 at 8:03 EST premarket
(UTC-5), https://stockanalysis.com/stocks/crwv/ . Single saved
observation in quote-baselines-release.json; not an execution price.
Separately November11 regular close USD60.77 at16:00EST. Current fully
diluted enterprise value/expectations gap not established.
DATE_FIRST_ADDED_TO_RADAR: 2026-10-01, earliest published card preserved
SETUP_TYPE: Actual-result renewal and financing test
ATTENTION_STAGE: Bullish renewal mechanism versus pricing-gap skepticism
ATTENTION_WINDOW: Actual receipt/financing disclosures over stated
next-three-month window
KEY_QUESTION: Can the paid-off fleet help fund growth while increasing
what each share retains?
THESIS_OBJECT_2: NBIS
THEME: Initial platform enablement versus recurring service and
cash/share conversion
STATUS: active_trackable; research candidate, initial enablement
confirmed, recurring economics unresolved
POSITION_CONTEXT: [not provided]
PRICE_AT_PUBLISH: USD 136.80, November12,2026 at 8:04 EST premarket
(UTC-5), https://stockanalysis.com/stocks/nbis/ . Single saved
observation in quote-baselines-release.json; not an execution price.
Separately November11 regular close USD154.69 at16:00EST. Current
fully diluted enterprise value/expectations gap not established.
DATE_FIRST_ADDED_TO_RADAR: 2026-11-10, original introduction preserved
SETUP_TYPE: Actual-report revenue-quality and delivery/cash test
ATTENTION_STAGE: Current revenue expectations tested against actual mix
ATTENTION_WINDOW: November 12 actual release, subsequently verified
call and disclosures
KEY_QUESTION: What initial work repeats and converts to cash when
partner capacity becomes available?
THESIS_OBJECT_3: IREN
THEME: Contract payment denominator, acceptance and ownership
STATUS: active_trackable; research candidate, commissioning/funding pending
POSITION_CONTEXT: [not provided]
PRICE_AT_PUBLISH: USD 19.44, November12,2026 at 8:03 EST premarket
(UTC-5), https://stockanalysis.com/stocks/iren/ . Single saved
observation in quote-baselines-release.json; not an execution price.
Separately November11 regular close USD20.84 at16:00EST. Current fully
diluted enterprise value/expectations gap not established.
DATE_FIRST_ADDED_TO_RADAR: 2026-11-10, original introduction preserved
SETUP_TYPE: Contract/funding comparability counterexample
ATTENTION_STAGE: Peer prepayment debate
ATTENTION_WINDOW: Actual accepted-capacity/funding updates;2027
milestone beyond review horizon
KEY_QUESTION: What does the customer fund and what costs/claims remain
for shareholders?
THESIS OBJECTS
THESIS_OBJECT_1 — CRWV
CARD_ID: WKAP-RADAR-2026-11-12-CRWV
CARD_TITLE: A Second Contract Has a Different Capital Bill
TYPE: trackable_wow
THEME: Paid-off-fleet renewals and retained AI-cloud economics
STATUS: active_trackable; research candidate, cash/share conversion pending
POSITION_CONTEXT: [not provided]
PRICE_AT_PUBLISH: USD 54.77, November12,2026 at 8:03 EST premarket
(UTC-5), https://stockanalysis.com/stocks/crwv/ . Single saved
observation in quote-baselines-release.json; not an execution price.
Separately November11 regular close USD60.77 at16:00EST. Current fully
diluted enterprise value/expectations gap not established.
DATE_FIRST_ADDED_TO_RADAR: 2026-10-01, preserved
ATTENTION_STAGE: Renewal opportunity repriced after actual Q3
ATTENTION_WINDOW: Receipt, service-cost and financing evidence
WHY_A_READER_CARES_NOW: The historical expansion cash gap does not
forecast permanent parent/equity capital needs once existing assets
enter another contract cycle.
PREVIOUS_STATE: June demand and funding evidence before the
now-observed November10 result.
CURRENT_STATE: Q3 operating improvement and wider historical cash gap
coexist with a verified management renewal/funding explanation.
DECISION_OR_MONITORING_PAYOFF: Keep realized cash, signed future
receipts and prospective renewals separate before valuing the benefit.
THESIS_SUMMARY
The specific agent connection is MasterClass's teaching-agent
evaluation and cloud delivery, alongside broader AI customers. No
allocation to a particular old fleet is disclosed. The second contract
can reuse sunk equipment and avoid its original associated asset loan;
service costs and replacement remain. Historical cash equipment
spending is not the deployment capex metric.
WKAP_ANGLE
The surface-level frame: either the cash gap guarantees endless
dilution or paid-off GPUs imply pure profit.
The alternative frame: renewal cash and expansion spending have
different asset stages; neither cancels the other.
The key research question: after actual receipts, delivery
obligations, corporate costs and ownership changes, what does each
share retain?
CORE_THESIS
Use WorksheetsA–D and the issuer Q3 release/transcript/presentation.
Expected greater-thanUSD 3bn renewal component is within approximately
USD 9bn near-term receipts, not an additional sum. The prospective
future renewal opportunity sits outside backlog and depends on
pricing. The conditional parent-level forecast assumes continued asset
financing and a committed-backlog investment path. Prepayments can
exchange pricing concessions for cheaper financing; compare economics
rather than celebrate cash alone. Stronger operating income is real
contrary evidence to a simple business-collapse story;
interest/losses/cash investment and dilution qualify its shareholder
implication.
ATTENTION_TRADE_FRAME
Attention Source: https://x.com/KyleReidhead/status/2120322446322499716
Why Today: November 11 full post elevates paid-off-fleet renewals after Q3.
Attention Stage: Independent bullish mechanism and valuation inference.
Attention vs Evidence
Hard evidence: reported financials and issuer-published management
statements; forecast outcomes not realized.
Primary sources: Q3 release, transcript and presentation linked above.
Attention / interpretation: largely pure-profit and underpricing
conclusions are not adopted; replies question future old-GPU prices
and whether renewal is already expected.
Attention Path: signed renewal → actual receipt → delivered service →
retained costs/cash → funded next capacity → diluted-share value.
Attention Asymmetry: old-asset funding economics can differ from the
new-build cash gap.
Crowding Risk: UNMEASURED; observed counters/replies do not measure positioning.
What Could Sustain Attention: received cash, durable renewal pricing
and completed attractive financing.
What Could Make Attention Fade: forecast opportunities mistaken for
contracted profit.
Attention-to-Thesis Conversion: evidenced retained cash plus a dated
valuation/expectations mismatch.
WEAKEST_ASSUMPTION: useful asset life, pricing and financing preserve
the incremental cash benefit after all claims.
MOST_IMPORTANT_DATA_POINT: actual renewal receipts reconciled with
ongoing service/replacement and company obligations.
NEXT_DATA_POINT: actual issuer financing/receipt/issuance updates
through https://investors.coreweave.com/ ; no invented future report
URL or promised disclosure date.
THESIS_OBJECT_2 — NBIS
CARD_ID: WKAP-RADAR-2026-11-12-NBIS
CARD_TITLE: Initial Platform Revenue Arrives Before Partner Capacity
TYPE: trackable_wow
THEME: Revenue recognition, recurring compute and cash/share conversion
STATUS: active_trackable; research candidate, initial enablement
confirmed, recurring economics unresolved
POSITION_CONTEXT: [not provided]
PRICE_AT_PUBLISH: USD 136.80, November12,2026 at 8:04 EST premarket
(UTC-5), https://stockanalysis.com/stocks/nbis/ . Single saved
observation in quote-baselines-release.json; not an execution price.
Separately November11 regular close USD154.69 at16:00EST. Current
fully diluted enterprise value/expectations gap not established.
DATE_FIRST_ADDED_TO_RADAR: 2026-11-10, preserved
ATTENTION_STAGE: Pre-results revenue hope meets actual accounting composition
ATTENTION_WINDOW: Actual November12 report, separately verified call
and subsequent conversion tests
WHY_A_READER_CARES_NOW: About325mUSD of980.8m group revenue is
explicitly non-recurring initial partner work; that requires a
different valuation test from repeatedly serving an agent.
PREVIOUS_STATE: Partner economics and actualQ3 unresolved.
CURRENT_STATE: Initial partner-enablement revenue confirmed; cloud
growth supported, delayed third-party execution weakened, recurring
partner profit/cash unresolved.
DECISION_OR_MONITORING_PAYOFF: Split enablement, service,
annualization and receipt before forecasting recurring margin/cash per
share.
THESIS_SUMMARY
Hark selected Token Factory for low-latency computer-use-agent
inference. The broader platform includes CPU-intensive execution,
sandboxes/runtime/routing, inference and search; not all revenue is
agent usage. Actual new letterp14 separately reports initial
approximately325mUSD non-recurring architecture/platform enablement on
partners' funded capacity. Revenue is earned at enablement and as
capacity comes online; small-scale partner capacity begins2027. The
same sale should not be counted again as later metered service without
contractual evidence. Sources:
https://assets.nebius.com/assets/5bc733ff-bed7-415c-af10-74ce7881a764/Nebius-SHL-2026-Q3.pdf?cache-buster=2026-11-12T11:54:28.601Z
; https://assets.nebius.com/assets/e2ac679c-fc62-4799-ba0e-6611e59c6863/Nebius-2026-Q3.pdf?cache-buster=2026-11-12T11:29:57.729Z
.
WKAP_ANGLE
The surface-level frame: strong AI-cloud revenue/ARR and prepayment
coverage prove recurring self-funded growth.
The alternative frame: deliverables, recognition, capacity, receipt
and owner claims have different dates/perimeters.
The key research question: what repeats and converts to retained cash
once initial work and residual funding/obligations are identified?
CORE_THESIS
WorksheetsA–D supply the exact tests. Cloud
revenue973.8mUSD/adjustedEBITDA518.2m/53.2% and four newly earning
sites are genuine favorable evidence against a collapse shortcut. But
the initial partnership revenue's costs/cash are not separately
supplied. Company explains that single-month ARR becomes choppy as
partnerships scale and will shift guidance metrics in2027; no
disclosed monthly split supports mechanically normalizing
September6.4bnUSD ARR by the quarter's one-off amount. Negative273mUSD
operating cash and7,300.4m purchases coexist with stronger contract
terms.
2026 revenue now targets the low end of3.0–3.4bnUSD while capex is
about27bn. Initial2027 revenue12–13bn/capex40–45bn and pre-tax
breakevenQ4 2027 assume five-year compute depreciation and future
delivery/funding. Expected75–85% capex coverage includes
investment-grade asset borrowing, not just prepayments. Actual shares,
convertibles, stock compensation and restrictions remain part of the
per-share bridge. The partner model can create valuable initial work
without proving a priced recurring-service opportunity.
ATTENTION_TRADE_FRAME
Attention Source: https://x.com/TopTechStocksUS/status/2120625745697640652
Why Today: A pre-results post asks for asset-light updates and hopes
for more than1bnUSD revenue; new report now answers composition, not a
social hurdle.
Attention Stage: One bullish account's prior expectation, not issuer
guidance or analyst consensus.
Attention vs Evidence
Hard evidence: new release/letter, actual quarterly financials and
stated current forecasts.
Primary sources: November12 PDFs above; actual issuer index
https://nebius.com/financials .
Attention / interpretation: revenue hope, claimed valuations and
auction prices are not adopted as source facts. Loaded replies praise
management or ask questions; praise does not establish execution or
cash.
Attention Path: initial enablement → recognition → partner capacity →
recurring work/costs → collections → financing/shares → retained
value.
Attention Asymmetry: headline growth and ARR are more visible than
which work is non-recurring and which cash is received.
Crowding Risk: UNMEASURED; observed views/replies are not consensus or holdings.
What Could Sustain Attention: repeatable source-backed
revenue/cost/cash and accepted delivery.
What Could Make Attention Fade: annualization repeated without mix,
costs or collection evidence.
Attention-to-Thesis Conversion: supported repeatable retained
economics plus a dated expectations gap and invalidator.
WEAKEST_ASSUMPTION: platform economics repeat and survive remaining
service, funding and ownership claims.
MOST_IMPORTANT_DATA_POINT: recurring/initial work and corresponding
costs/collections, with accepted partner capacity.
NEXT_DATA_POINT: separately verified public13UTCcall materials and
subsequent reported conversion. No completed Q&A or future result is
assumed from a start time.
THESIS_OBJECT_3 — IREN
CARD_ID: WKAP-RADAR-2026-11-12-IREN
CARD_TITLE: Ninety Percent of Which Bill?
TYPE: trackable_wow
THEME: Contract payment denominator, acceptance and ownership
STATUS: active_trackable; research candidate, commissioning/funding pending
POSITION_CONTEXT: [not provided]
PRICE_AT_PUBLISH: USD 19.44, November12,2026 at 8:03 EST premarket
(UTC-5), https://stockanalysis.com/stocks/iren/ . Single saved
observation in quote-baselines-release.json; not an execution price.
Separately November11 regular close USD20.84 at16:00EST. Current fully
diluted enterprise value/expectations gap not established.
DATE_FIRST_ADDED_TO_RADAR: 2026-11-10, preserved
ATTENTION_STAGE: Current peer-contract comparison
ATTENTION_WINDOW: Actual acceptance/receipt/financing updates
WHY_A_READER_CARES_NOW: Different prepayment percentages can measure
different obligations and cannot rank shareholder economics by
themselves.
PREVIOUS_STATE: Revised commissioning target and stated funded perimeter.
CURRENT_STATE: The contract's90% GPU-capex denominator is clear; full
total-contract-value conversion is not disclosed.
DECISION_OR_MONITORING_PAYOFF: Compare what the customer buys and what
the company still funds, then test commissioning.
THESIS_SUMMARY
September services135m and finance-lease65m contribute different
accounting economics to200m AI-cloud revenue. Neither is exclusively
agent inference. The86% segment gross margin excludes
depreciation/amortization and precedes site costs; it cannot stand in
for fully burdened retained cash. Greater-thanUSD 4bn ARR targets
January 31, potentiallyFebruary 2027, after design/supplier timing
changes.
WKAP_ANGLE
The surface-level frame: the bigger advance percentage is
automatically the better business.
The alternative frame: GPU capex, owned-site investment and total
contract value have different bases.
The key research question: which obligations remain after the advance,
and does actual accepted service produce cash per diluted share?
CORE_THESIS
The filed post-quarter five-year contract has90% GPU capex prepaid.
Retain its specific scope rather than apply it to all contracts.
Broader available cash, restrictions, undrawn commitments and
unreceived advances remain separate. ARR annualizes commissioned
contracted GPU-hour pricing plus ancillary charges, unlike Nebius's
final-month revenue annualization. Renewal economics at another
provider cannot cure IREN's uncompleted commissioning or prove an
attractive stock price. Funded delivery, operating costs, replacement
and dilution determine the result.
ATTENTION_TRADE_FRAME
Attention Source: https://x.com/jiahanjimliu/status/2120399373389672926
Why Today: November 11 full post compares90% GPU capex with up to 100%
total contract value.
Attention Stage: Independent contract/economic model, not issuer or consensus.
Attention vs Evidence
Hard evidence: filed90% denominator, service/lease split, margin
exclusions and revised timeline.
Primary sources: November 5 SEC exhibit linked above and CoreWeave
issuer transcript.
Attention / interpretation: Jim's65% total-value conversion is not
adopted; replies challenge colocation-versus-owned-site assumptions
and the distinction between contract value and delivery capex.
Attention Path: advance → equipment/site obligations →
commissioning/acceptance → recognition/collection →
financing/replacement → share retention.
Attention Asymmetry: the funding percentage is more visible than its
denominator and remaining service costs.
Crowding Risk: UNMEASURED; engagement does not establish positions.
What Could Sustain Attention: actual received funding and accepted
revenue-producing capacity.
What Could Make Attention Fade: numerical contract comparisons without
comparable underlying terms.
Attention-to-Thesis Conversion: retained economics and an expectations
mismatch, not advances alone.
WEAKEST_ASSUMPTION: accepted delivery and funding terms preserve
modeled cash after operating/replacement and ownership costs.
MOST_IMPORTANT_DATA_POINT: commissioned capacity matched to
services/lease recognition and actual available funds.
NEXT_DATA_POINT: actual issuer reports/SEC disclosures; do not invent
a milestone before January 2027 or call silence failure.
CROSS_OBJECT_ATTENTION_COMPARISON
Cross-Object Attention Comparison
Rank | Object | Attention Asymmetry | Evidence Quality | Catalyst
Clarity | Crowding Risk | Attention Window | Conversion Potential
1 | NBIS | Initial enablement versus recurring headline | Actual new
report, future conversion unresolved | Public call and next mix/cash
update | UNMEASURED | Reporting then accepted capacity | Conditional
repeatable retention
2 | CRWV | Paid-off fleet versus surviving bill | Actual quarter and
expected signed receipts | Receipt/financing evidence | UNMEASURED |
Stated receipt window | Conditional renewal cash
3 | IREN | Service/lease and advance bases | Filed definitions and
target | Acceptance/funding | UNMEASURED |2027 milestone beyond review
horizon | Conditional delivery
Cleanest Attention Trade: NBIS for the revenue-composition question,
not expected return. Most Evidence-Backed Attention Trade: NBIS's new
actual disclosure; CRWV remains the fuller renewal comparator, not a
certainty ranking. Most Crowded Attention Trade: UNMEASURED. Highest
Fade Risk: an annualized or non-recurring headline treated as owner
cash. Best Candidate to Become a Durable Thesis: no unconditional
winner; require repeatable retained economics and price/expectations
evidence.
7_DAY_RESEARCH_WORKFLOW
CRWV — 7-Day Checks
Through the actual issuer index retrieve receipt, loan,
ATM/convertible and filing updates. Classify completed versus expected
facilities and separate asset from parent finance. Compare
useful-life/pricing and service costs on actual renewals; do not
extend current prices mechanically through2028. If no new data after a
bounded search, retain current known facts and pending forecast
status.
NBIS — 7-Day Checks
Reconcile new report with public call/replay/transcript when actually
accessible through issuer links, without assuming completed Q&A or
accepting new terms. Track initial/repeated partner work, its costs,
recognition and receipts separately from accepted available capacity.
Preserve actual Q3 signed9M−H1 reconciliation, new delayed tranches
and stronger funding terms. Record undisclosed disaggregation
unavailable; do not force a normalized ARR/profit estimate. The
original seven-day review isNovember17, not reset by this new report.
IREN — 7-Day Checks
Follow actual reports and SEC links for commissioning/customer
acceptance, recognized services/leases, receipts and financing
conditions. Match the prepayment denominator to the contract's full
remaining obligations. Preserve the January 31/possibleFebruary 2027
window; a seven-day review cannot judge a later milestone as failed
merely because it is not complete yet.
Cross-Object — 7-Day Checks
This is a follow-up of the November 10 cohort, with QQQ, November 17
and December 10 retained rather than reset by a second Article. First
completed regular close after November 10 publication is November 10
at16:00 EST/21:00 UTC. Alternate-provider Stock Analysis
adjusted-close baseline captured November 11:
CRWV48.73/NBIS134.00/IREN19.73/QQQ674.76USD. Pair future endpoints
from that same provider and preserve adjustment/corporate-action
methodology and capture times. Baseline capture is not an outcome; no
benchmark or deadline switching after observing returns.
Primary-source retrieval registry: CRWV:
https://investors.coreweave.com/ ; NBIS:
https://nebius.com/investor-events ; IREN:
https://www.iren.com/investors/reports . Follow actual dated issuer
links, never guessed future reports.
Attention-source retrieval registry: CRWV:
https://x.com/KyleReidhead/status/2120322446322499716 ; NBIS:
https://x.com/TopTechStocksUS/status/2120625745697640652 ; IREN:
https://x.com/jiahanjimliu/status/2120399373389672926
Evidence-state snapshot: CRWV=reported operating
progress,signed-renewal-receipt expectation,retained cash
pending;NBIS=initial non-recurring enablement confirmed,cloud growth
supported,delivery timing weakened,recurring economics/cash
unresolved;IREN=filed contract/definition supported,acceptance/funding
conditional;classification=trackable_wow;rule=business components
separate from price;expectations-gap=not established.
30_DAY_RESEARCH_WORKFLOW
CRWV — 30-Day Checks
Validate actual expected-receipt progress and financing terms against
the scenario. Upgrade retained-value evidence only after
service/replacement and share claims are considered. Weaken on
observed old-fleet pricing/utilization or receipt/funding
deterioration; invalidate the specified mechanism only on
contradictory primary evidence. Do not use a price decline as business
invalidation or equate parent capital with consolidated borrowing.
NBIS — 30-Day Checks
Validate subsequent repeatable partner/platform work, accepted service
and collections after matching costs/funding/shares. Upgrade only the
confirmed component, not the whole business from a reported growth or
ARR number. Weaken on further delivery or retained-value
deterioration; invalidate the specified repeatable-cash mechanism only
on contradictory evidence. Keep unknown monthly/partner splits
unknown. Preserve the older separate NBIS/SPY cohort and its own
horizons; this November10 cohort remainsQQQ/December10.
IREN — 30-Day Checks
Validate actual acceptance/recognition and availability of funds.
Upgrade delivered retained economics only on evidence; weaken on new
documented pushouts or value-eroding financing. Keep December 10
earlier than the January/February 2027 milestone. Contracted demand
may remain strong even if a specific delivery/funding component
weakens.
Cross-Object — 30-Day Checks
December 10 retains the original precommitted QQQ baseline and
adjusted-price method. Freeze business-component verdicts before
reading returns; report confirmed, weakened, invalidated, pending and
unavailable cases. Separate business progress from stock/benchmark
performance and avoid factor-neutral alpha claims. NO_NEW_DATA
preserves source-backed status and returns to the next existing
review; it does not authorize a new monitor, trade or changed horizon.
WKAP DAILY TOP 3
Three market sources worth feeding into today’s market chat. Not
required reading — WKAP has already extracted the signal.
1. @KyleReidhead — The Old Fleet Gets Another Contract
URL: https://x.com/KyleReidhead/status/2120322446322499716
WKAP signal: Paid-off equipment can change incremental funding
economics; reject largely-pure-profit and underpricing conclusions
without cost and expectations evidence.
Why it matters today: The new quarter and issuer transcript make
signed near-term receipts distinct from prospective current-price
renewals.
Themes/tickers: AI-cloud renewal cash, CRWV.
Question to ask: What actual receipts, service costs, replacement and
diluted ownership would demonstrate retained value beyond what the
current price assumes?
2. @TopTechStocksUS — Revenue Hopes Meet an Accounting Map
URL: https://x.com/TopTechStocksUS/status/2120625745697640652
WKAP signal: Pre-results more-than1bnUSD revenue hope and request for
asset-light updates are one account's expectations, not
guidance/consensus. Other valuation/auction assertions are not
adopted.
Why it matters today: Actual980.8mUSD group revenue includes
approximately325m non-recurring initial enablement; partner capacity
small-scale2027 is a separate stage. The social number is not our
cohort's pass/fail rule.
Themes/tickers: Revenue composition, platform economics and ownership, NBIS.
Question to ask: What costs, receipts and subsequent repeatable work
would turn initial platform enablement into durable cash per share?
3. @jiahanjimliu — Check the Prepayment Denominator
URL: https://x.com/jiahanjimliu/status/2120399373389672926
WKAP signal: Ninety percent of GPU capex and up to100% of contract
value fund different bills; the post's total-value conversion and
colocation assumptions remain opinions.
Why it matters today: Peer funding enthusiasm can obscure IREN's owned
infrastructure, remaining obligations and commissioning test.
Themes/tickers: Contract comparability, funded capacity, IREN.
Question to ask: After putting both contracts on a comparable cost and
service basis, what cash and ownership claims remain with the
provider?
Edition_version: 1
Cover_image_source_url:
https://pbs.twimg.com/media/HW7PX8hbIAAseO9?format=jpg&name=medium
Cover_image_sha256:
ec4ee1b054550905934dc933dd7c9b34e93b48d158671c99a1242802f1d563dc
Cover_logo_verified: true